Knowledge · Money & invoicing
Construction withholding tax and the exemption certificate under § 48 EStG
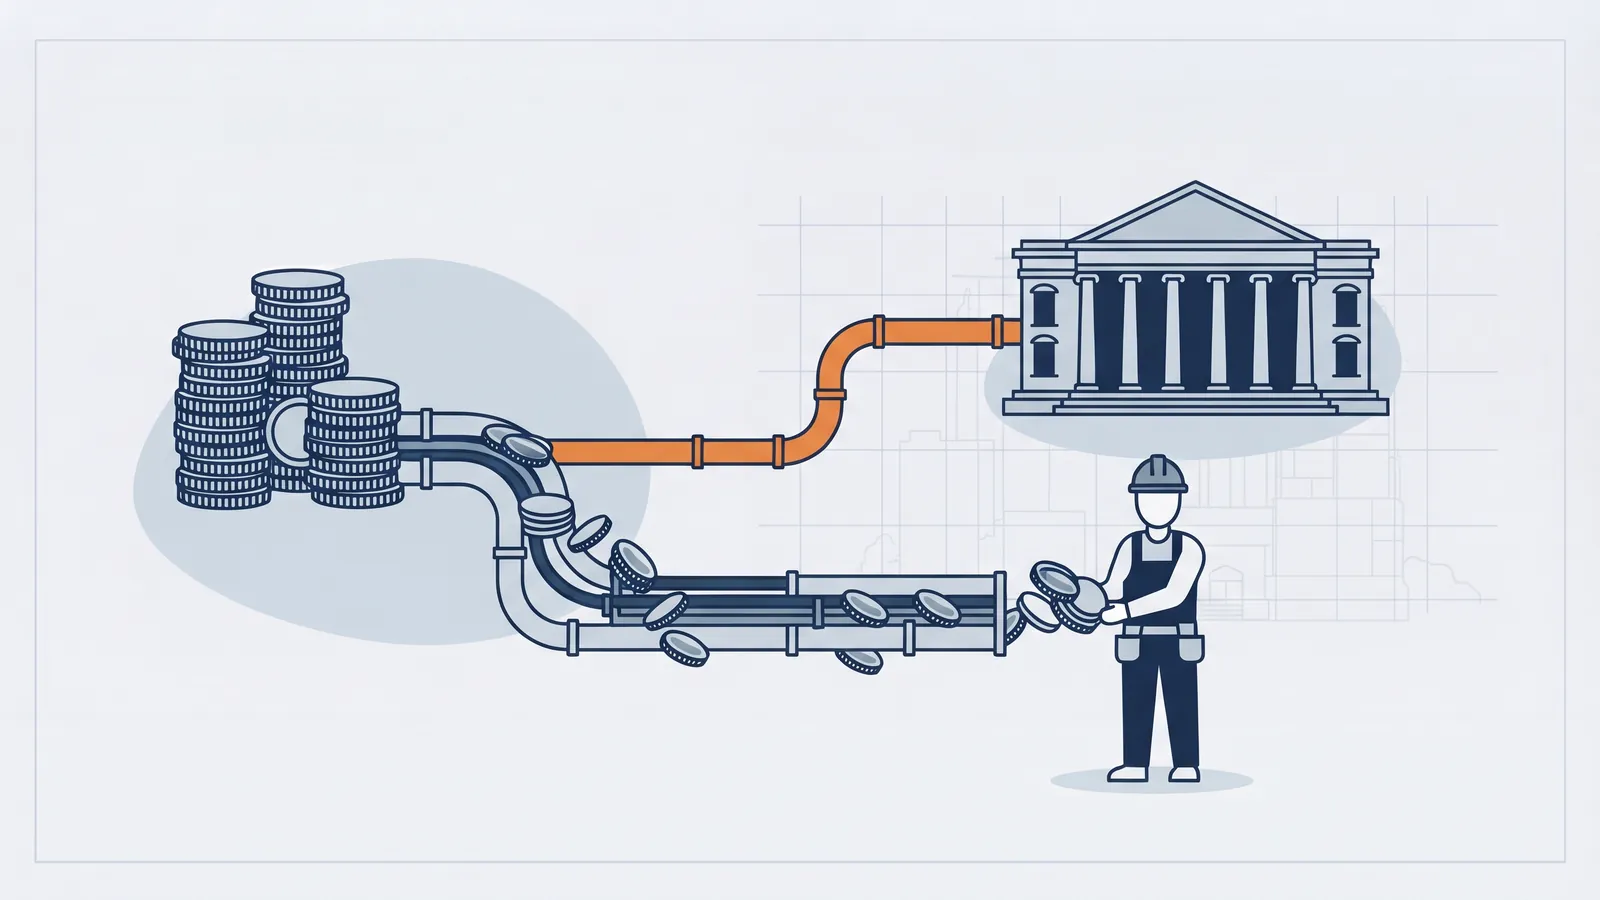
If you provide construction services to a business, you often receive 15 per cent less money unless a valid exemption certificate exists. A client (Auftraggeber) who ignores this is liable.
Last updated 20.10.2026 · 5 min read · Provisions checked against the statute and VOB text
Key points at a glance
- The client (a business or a public-law legal entity) must withhold 15 per cent of the consideration for the account of the service provider (§ 48 para. 1 EStG).
- No withholding with a valid exemption certificate or below the de minimis limit of 5,000 euros per calendar year (15,000 euros if the recipient only has tax-exempt rental turnover).
- The consideration is the payment plus VAT (§ 48 para. 3 EStG).
- Filing and payment by the 10th day after the end of the month in which the consideration is provided (§ 48a para. 1 EStG).
- Anyone who does not pay, or pays too little, is liable (§ 48a para. 3 EStG). An exemption certificate they were entitled to rely on protects them.
What construction withholding tax is about
The construction withholding tax (Bauabzugsteuer) is meant to prevent tax losses in the construction sector. The recipient of the service pays part of the remuneration directly to the service provider’s tax office. This affects you on both sides: as a subcontractor, when a general contractor reduces your invoice, and as a client, when you award trades to other businesses.
According to § 48 para. 1 sentence 3 EStG, construction services are all services that serve to produce, repair, maintain, alter or remove buildings.
Who has to withhold?
The recipient of the service is obliged to withhold if it
- is a business within the meaning of § 2 UStG (including small businesses and landlords) or
- is a public-law legal entity.
Private clients who do not obtain the service for business purposes are not affected. If the recipient rents out flats, § 48 para. 1 sentence 1 EStG is not to be applied to construction services for those flats if it rents out no more than two flats (§ 48 para. 1 sentence 2).
A person who bills for a service without having provided it is also treated as the service provider (sentence 4).
When does the withholding not apply?
The tax withholding does not have to be made if (§ 48 para. 2 EStG):
- the recipient of the service holds a valid exemption certificate under § 48b EStG at the time of the consideration, or
- the consideration is expected not to exceed the following in the current calendar year: 15,000 euros if the recipient carries out only tax-exempt turnover under § 4 no. 12 sentence 1 UStG (letting), otherwise 5,000 euros.
For the de minimis limit, all construction services for the same recipient are added up, including those still expected to be provided (§ 48 para. 2 sentence 2).
How is it calculated?
The consideration is the payment plus VAT (§ 48 para. 3 EStG). The withholding is 15 per cent of it. Example: invoice for 10,000 euros net plus 19 per cent VAT (11,900 euros gross): withholding 1,785 euros, payout 10,115 euros.
How the withholding is calculated for invoices issued without VAT under § 13b UStG is a frequent point of dispute. Clarify it with your tax adviser.
Filing and settlement
The recipient of the service must (§ 48a EStG):
- submit an electronic filing by the 10th day after the end of the month in which the consideration is provided, and calculate the tax withholding itself,
- pay the amount to the tax office responsible for the service provider on the 10th day after the end of the filing period, for the account of the service provider,
- settle with the service provider and state: name and address of the service provider, invoice amount, invoice date and payment date, amount of the tax withheld and the tax office where the filing was made.
The service provider can have the amount paid over credited against its tax liability.
The exemption certificate
As a contractor (Auftragnehmer), you apply for the exemption certificate at the tax office (§ 48b EStG). It tells the customer that it does not have to withhold. It is valid for three years at most from issue, can be limited to individual projects and must be available to the client before payment (BMF information sheet on tax withholding on construction services, as at April 2025).
As a client, you should:
- check before every payment whether a valid certificate exists and has not expired,
- query the authenticity and validity with the tax authorities (online query at the Federal Central Tax Office),
- put a copy in the project folder.
As a contractor, you should:
- renew the certificate in good time before it expires,
- send customers the current version before the first invoice is issued,
- note which customer has which certificate.
Liability
The recipient of the service is liable for an amount of withholding that was not paid or was paid too low (§ 48a para. 3 sentence 1 EStG), regardless of whether it is at fault. It is not liable if it held an exemption certificate at the time of the consideration whose lawfulness it could rely on. This does not apply if the certificate was obtained by improper means or false information and it knew this or was grossly negligent in not knowing (sentence 3).
The de minimis limit is a forecast: if it is exceeded during the year, a withholding may become necessary. Keep an eye on the total per recipient.
What you should not mix up
- Construction withholding tax (§ 48 EStG): advance payment of the service provider’s income tax / corporation tax. Filed by the client.
- Reverse charge under § 13b UStG: VAT. The client owes the tax. Both rules can apply at the same time.
Frequently asked questions
Does the construction withholding tax also apply to private customers?
No. It affects recipients of services who are businesses or public-law legal entities. A private person who builds does not have to withhold anything.
How long is an exemption certificate valid?
It says so on the certificate. It is time-limited; check that it is valid at the time of payment.
From what amount do I have to pay it over?
If the consideration for the same recipient is expected to exceed 5,000 euros in the calendar year (15,000 euros for exclusively tax-exempt letting) and no exemption certificate exists.
What happens if I forgot to withhold?
You are then liable for the amount not paid over (§ 48a para. 3 EStG). Talk to your tax adviser without delay about filing late.
Who settles the 15 per cent with the tax office?
The recipient of the service files and pays it over. The service provider has the amount credited if it has the settlement under § 48a para. 2 EStG.
Sources and status
- § 48 EStG – tax withholding (checked against the statutory text in the BauWalker corpus)
- § 48a EStG – procedure
- § 48b and § 48c EStG – exemption certificate, crediting (checked against the statutory text in the BauWalker corpus)
- BMF information sheet on tax withholding on construction services (as at April 2025): amount, exemption limits, filing, validity, liability
- Stand: 19.10.2026. The detailed BMF circular on construction withholding tax was not evaluated. For the calculation in an individual case, seek tax advice.
- Quotations of statutory text are given in translation; the German wording is authoritative.
How it works in BauWalker
BauWalker prepares invoices and letters as drafts when you describe the task. Tax questions about the construction withholding tax you clarify with your tax adviser.
This material is for information and is not legal or tax advice. The specific consequences depend on your contract and the circumstances on the construction site.
Keep reading
Invoice without VAT: § 13b UStG for construction services (reverse charge)
When the client owes the VAT, what note the invoice needs, which certificate you should ask the customer for and what applies in the event of a mistake.
Schlussrechnung (final invoice) under VOB/B: deadline, verifiability, payment
By when the final invoice must go out, what verifiable means, when the money falls due and how the reservation on final payment works.
Create documents – invoice, quote, change order
Invoice, quote, change order, letter and acceptance report: you describe the task in your language, BauWalker prepares the document in German.